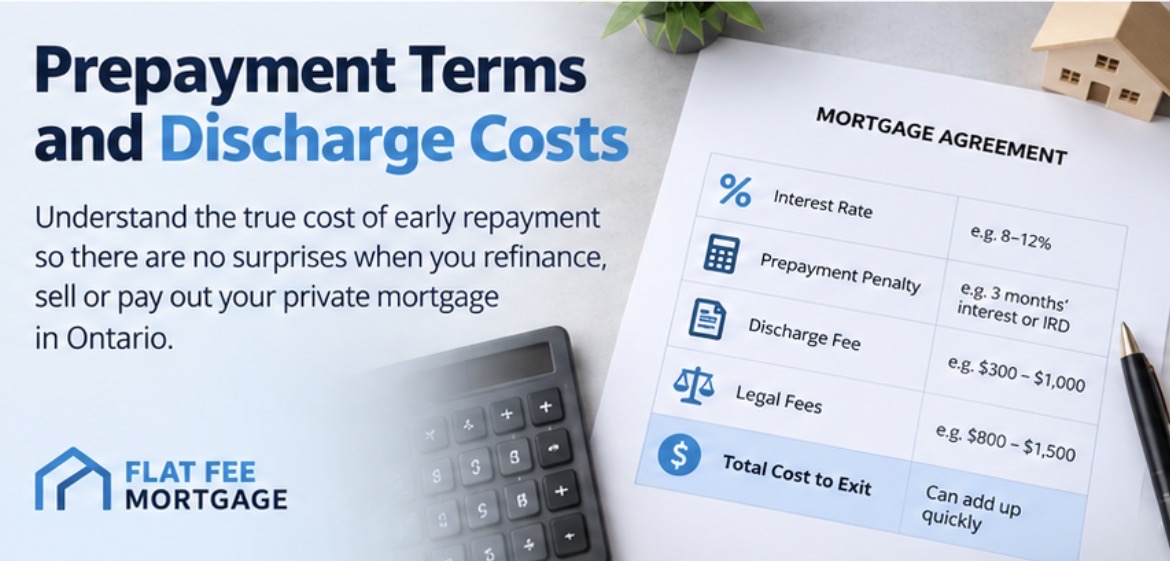
Prepayment terms affect your flexibility to make extra mortgage payments, while early-exit penalties and discharge fees can add costs when you end the mortgage. Compare these features alongside interest costs—not the rate alone. Ontario’s Financial Services Regulatory Authority (FSRA) identifies each as something borrowers should investigate, but its guidance does not establish which mortgage will be cheaper for you.[E1]
Separate extra payments, early exit and discharge
These are distinct parts of the comparison:
- Prepayment flexibility: FSRA recommends comparing options such as extra monthly payments and annual lump sums.[E1] Ask what your contract permits, when you can use those privileges and what happens if you exceed them. A feature is useful only if it fits the payments you realistically expect to make.
- Early-exit or renegotiation costs: FSRA advises asking whether breaking or changing the contract before the term ends carries penalties or fees, and how they are calculated.[E1] Do not rely on an “open,” “closed” or “convertible” label instead of checking the actual conditions.
- Discharge fees: FSRA lists discharge fees separately from early-breaking penalties.[E1] Ask whether a discharge fee applies to your transaction, how it is calculated and what the quoted amount includes. An answer about the penalty alone does not resolve the discharge-cost question.
The guidance supplies neither a standard penalty formula nor a standard discharge fee. Your contract and the applicable lender fee information are needed to establish those amounts.[E1]
Compare against your likely plans
If you expect to make extra payments, compare the permitted payment increases and lump sums with your intended amounts and timing. Ask for a comparison using the same payment plan for each mortgage rather than assuming a more flexible product is automatically cheaper. FSRA identifies payment frequency, amortization and payment amounts as factors affecting total cost.[E1]
If you may sell or refinance, ask for the potential early-exit charges and discharge fees to be shown separately. If you may move to another property, also ask about portability—the option to transfer the mortgage, including its rate, to that property—and the conditions for using it.[E1]
Keep the term separate from the amortization: the term is the period covered by the specific mortgage contract; amortization is the period for repaying the mortgage through regular payments.[E1] Your comparison should address when you expect to leave the contract, not just when the mortgage would eventually be paid off.
Get a transaction-specific explanation before deciding
When working with an Ontario mortgage brokerage, ask for an explanation of potential discharge and administrative fees, renewal charges and material risks. FSRA’s brokerage guidance identifies these disclosure subjects and says standard contract terms alone are insufficient disclosure of material risks.[E2] This is brokerage-specific guidance, not a uniform fee schedule for every lender or private mortgage.
Decision rule: compare interest costs and applicable charges under the same realistic repayment and exit plan. Give flexibility weight when you expect to use it, but do not assume it outweighs other costs. Without the mortgage terms, fee information and your planned payment or exit timing, no reliable dollar comparison—or conclusion that early repayment or refinancing saves money—can be made.
Sources
- [E1] Shopping for a Mortgage | Financial Services Regulatory Authority of Ontario — retrieved 2026-10-05T09:11:04.567Z
- [E2] Mortgage brokerage disclosure requirements | Financial Services Regulatory Authority of Ontario — retrieved 2026-10-05T09:11:16.668Z